Table of Content
This Internet-based application can establish eligibility and issue an online COE in a matter of seconds. Not all cases can be processed through Web LGY - only those for which VA has sufficient data in our records. However, Veterans are encouraged to ask their lenders about this method of obtaining a certificate. There is no down payment required for VA loans up to $1,094,625. For example, let’s say you’ve found the house of your dreams, and it’s going to cost $647,200.

Veterans who are eligible for a VA loan have VA loan entitlement, which is basically a dollar amount the VA promises to repay back to a lender in the event you default on your mortgage. Home buying process for Veterans Get more information about using your VA home loan benefit to buy a home. The VA Entitlement code located at the top of the Certificate of Eligibility details the nature of service eligibility for a qualified veteran, active military member, or military spouse.
Multiple VA Loans
And, once you complete this one-time restoration, your COE will always have a notation about it. Consequently, to restore your VA loan entitlement again, the Department of Veterans Affairs will mandate that you sell all properties purchased with a VA loan. Meet lender qualifications for a VA loan (simply having VA entitlement doesn’t guarantee loan approval, as veterans still need to meet lender credit, income, and debt requirements).
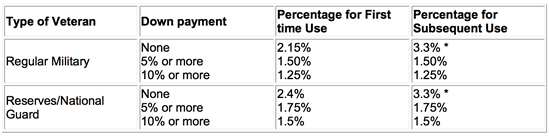
Calculating your remaining VA Entitlement can be done on your own or with the help of an experienced lender. Basic, 2nd Tier, and remaining entitlement calculations are the most common we see with the home buyers we work with. If your COE says “PIF No Restoration,” it means your VA loan was paid in full but you haven’t applied for restoration. Borrowers with full entitlement have no hard limit of how much they can borrow without a down payment. Again, that’s not to say a lender will give you a $2.5 million mortgage when you make $50,000 per year, just that there’s no limit enforced by the VA.
VA Entitlement Calculator: How Much Entitlement Do I Have?
Your length of service or service commitment, duty status and character of service determine your eligibility for specific home loan benefits. VA Home Loans are provided by private lenders, such as banks and mortgage companies. VA guarantees a portion of the loan, enabling the lender to provide you with more favorable terms. Eligible Veterans, service members, and survivors with full entitlement no longer have limits on loans over $144,000. This means you won’t have to pay a down payment, and we guarantee to your lender that if you default on a loan that’s over $144,000, we’ll pay them up to 25% of the loan amount. VA loan funding fee Find out if you'll need to pay this fee when using your home loan benefits.

However, the rules are a tad different when you have a reduced entitlement. Since the VA guarantees up to 25% of your loan amount, you can determine your remaining entitlement by multiplying the loan amount by 25%. When you receive your Certificate of Eligibility , the basic entitlement shown on the loan is $36,000. Importantly, $36,000 isn’t the limit of how much you can borrow. Instead, it’s a reflection of how much the VA will guarantee on the loan.
Get help from Veterans Crisis Line
If you meet minimum loan requirements, most lenders will loan you up to four times the basic entitlement without requiring a down payment. If you have already used your VA entitlement before, you may not be able to access the full amount. With this bonus entitlement, you won’t encounter loan limits set by the Department of Veterans Affairs. However, you’ll likely encounter a limit imposed by the lender that considers your income, credit, and other financial details.
Use the LendingTree home affordability calculator to estimate what amount that is for you, based on your income, debt and the likely monthly costs of owning a home. Multiply that number by 4 to arrive at the maximum loan amount you can take out without having to make a down payment. You are an active-duty service member who has served for 90 consecutive days. You use at least a portion of your entitlement when you buy a home with a VA loan.
What Is VA Entitlement And How Does It Work?
When you have full entitlement, the VA doesn’t impose a loan limit. With that, you can borrow as much as a lender is willing to provide without a down payment. Information, rates and programs are subject to change without notice. You can also use the VA Loan to purchase a home with a maximum loan amount that’s equal to or less than the remaining entitlement.

Let’s say you previously used a VA loan to purchase your current home for $300,000 and you’ve just received permanent change of station orders. You plan to buy a home at your new duty station, but can’t sell your current home and have your VA loan entitlement restored. This means you’ll have to buy your home with your remaining entitlement. If your entitlement is reduced, the VA will only guarantee your loan up to the conforming loan limit, minus the entitlement you’re currently using. We’ll go over exactly how to figure out your reduced entitlement amount further down. If you have remaining entitlement for your VA-backed home loan, find out the current loan limits and how they may affect the amount of money you can borrow without a down payment.
With remaining entitlement, your VA home loan limit is based on the county loan limit where you live. This means that if you default on your loan, we’ll pay your lender up to 25% of the county loan limit minus the amount of your entitlement you’ve already used. Of course, lenders aren’t going to approve any loan amount just because you’re eligible for a VA loan. If you meet minimum loan requirements, most lenders will approve up to four times what is known as “basic” VA entitlement without requiring a down payment.
On your COE, in the table called Prior Loans charged to entitlement, we list the amount of your entitlement you’ve already used under the Entitlement Charged column. Your entitlement can be restored when you sell your property and pay your VA-backed loan in full, or repay in full any claim we’ve paid. If you apply and are eligible for a VA-backed home loan, you’ll receive a Certificate of Eligibility . This is the document that tells private lenders that you have VA home loan eligibility and entitlement.



No comments:
Post a Comment